The Honest Price Of Protecting Your Family.
Term life is the simplest insurance there is: a fixed monthly premium, a fixed number of years, a tax-free check to the people you name. We quote it across the carriers we represent — no single-carrier push, no return-of-premium upsell — and many applicants get a decision without an exam.
No obligation · No added cost — carriers pay us · Licensed in all 50 states + DC
A 30-second explainer with music. Illustrative stock photography; no real customers or staff.
Source: 2026 Insurance Barometer Study, LIMRA and Life Happens. About three-quarters of consumers overestimate what life insurance costs; adults under 31 overestimate a $250,000, 20-year term policy by roughly five to six times (2026 Barometer).
One Job. Done Cheaply.
Term life has no cash value, no investment sleeve, no "living benefits" sales pitch that doubles the premium. It pays a death benefit if you die during the term. That focus is why a healthy 30-year-old can lock a 20-year, $500,000 policy for less than most streaming bundles — and why the same person buying whole life pays many times more for the same death benefit.
- Level premium: the monthly price is guaranteed for the whole term — 10, 15, 20, 25, 30, even 35 or 40 years at some carriers.
- Income-tax-free payout: the death benefit is generally excluded from the beneficiary's income under IRC §101(a).
- Convertible: most term policies let you convert to permanent coverage later without a new exam, inside a window set by the carrier.
- Riders you actually use: accelerated death benefit for terminal illness, child riders, waiver of premium.
What A $500,000, 20-Year Policy Costs — The Honest Answer
It depends on four things the carrier can measure: age, sex, tobacco use and health class. Published benchmark quotes for a healthy (Preferred, non-smoking) applicant buying $500,000 of 20-year term: about $213 a year for a 30-year-old man and $182 for a 30-year-old woman — under $18 a month. The same man at 40 is quoted about $321 a year; at 50, about $810; at 60, about $2,335. A 30-year-old smoker: about $788 a year.
Source: NerdWallet average life insurance rates, Oct 2026 (means of the three lowest quotes, valid Oct 1, 2026; not a guaranteed rate).
Share of adults citing each reason for not owning (or not owning more) life insurance. Source: 2025 Insurance Barometer Study, LIMRA and Life Happens (reasons for not owning, or not owning more, life insurance).
Find Your Benchmark In Two Taps
Published 20-year, $500,000 benchmarks by age and profile (NerdWallet, Oct 2026). Tap, then carry your answers straight into a quote request.
$500,000 of 20-year term, Preferred class; means of the three lowest quotes among surveyed carriers, valid Oct 1, 2026. Source: NerdWallet average life insurance rates, Oct 2026. Monthly equivalents are the annual figure divided by 12; carriers add a modal fee for monthly billing. These are benchmarks, not an offer.
How Much Coverage? The One-Tap Rule Of Thumb
Ten times annual income is the quick estimate (more with young children or a mortgage; the DIME calculator is the careful version). Tap an income, then carry the amount into a quote request.
A rule of thumb, not advice. Carriers cap coverage by income and age; the agent confirms the amount that can be issued.
How Much, How Long, How Fast
The quick estimate: 10 times annual income, more with young children or a mortgage. The DIME method (debts, income, mortgage, education) gets closer. Run the calculator →
Match the term to the obligation: the years until the youngest is independent, or until the mortgage is paid. Choosing a length →
Accelerated underwriting checks prescription, driving and credit-based records instead of an exam. Fidelity Life approves up to $1,000,000 this way; Legal & General America up to $4,000,000 and Ethos up to $3,000,000 for qualifying applicants. No-exam term →
Licensed Agents, Not A Lead Farm
Your request stays with the licensed agents of our operating agency. It is not sold to a list of strangers. Ambient video is an illustrative render.
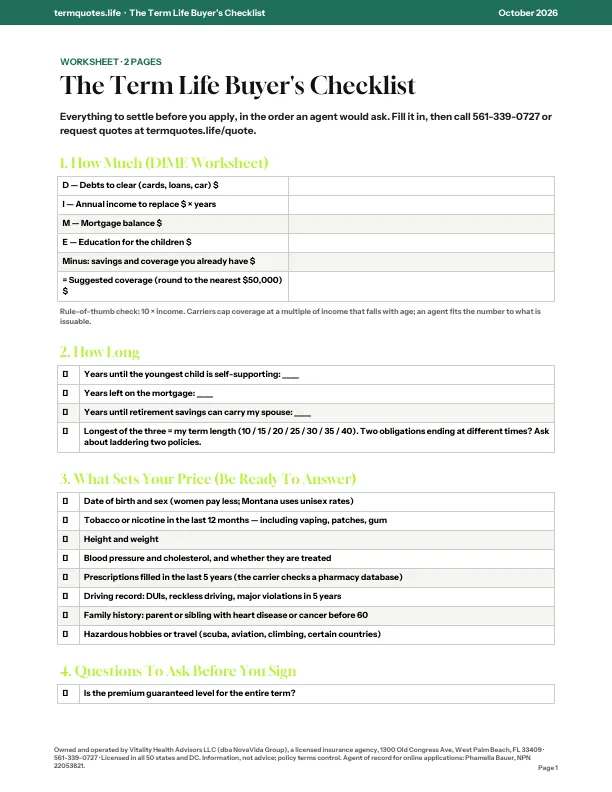
The Term Life Buyer's Checklist
Two pages: the DIME worksheet, how to pick a term length, the eight things that set your price, and the questions to ask before you sign.
- Fill it in before you call — the quote takes five minutes instead of twenty
- Carrier-sourced, dated, no sales copy
- Opens instantly after you submit
Pick The Door That Fits You
Talk To A Licensed Agent
Fastest way to a real number: 10 minutes, every carrier we represent, no pressure. Business hours, Eastern time.
Call 561-816-3446Request Quotes In 60 Seconds
Tell us age, state, coverage and health in one short form. A licensed agent emails or texts quotes, then you decide.
Request QuotesQuote & Apply On My Own
Prefer to do it yourself? Open a carrier tool, answer the questions, get a decision — many applicants in minutes.
You will leave this site for a carrier or partner tool. Any rate shown is an estimate until the carrier confirms it; the agent of record is Phamella Bauer (NPN 22053821), NovaVida Group.
Need more than $1,000,000, a 35- or 40-year term, or a carrier above? That is agent territory — call 561-816-3446 and we quote the full table.
19 Term Carriers In One Quote
Banner, Protective, Prudential, Corebridge, MassMutual, Mutual of Omaha, Pacific Life, Transamerica and more — the carriers in our Brokers Alliance product library, plus instant-decision carriers for people who want it done today. Independent means the recommendation is not tied to one logo.
See The Carrier Table
The carriers behind our term quotes
 Banner Life (Legal & General America)Quote this carrier →
 Corebridge Financial (American General)Quote this carrier →
 EthosQuote this carrier →
 Fidelity LifeQuote this carrier →
 Foresters FinancialQuote this carrier →
 John HancockQuote this carrier →
 Lincoln FinancialQuote this carrier →
 MassMutualQuote this carrier →
 Minnesota Life (Securian)Quote this carrier →
 North AmericanQuote this carrier →
 Pacific LifeQuote this carrier →
 Protective LifeQuote this carrier →
 Prudential (Pruco Life)Quote this carrier →
 SymetraQuote this carrier →
 TransamericaQuote this carrier →
 United of Omaha (Mutual of Omaha)Quote this carrier →
 William Penn (NY)Quote this carrier →
Carrier names and logos identify the companies whose products are available to quote through our brokerage relationships; they do not imply endorsement of this site by any carrier. Availability varies by state.
Questions People Ask Before They Buy
How much does term life insurance cost?
For a healthy 30-year-old, published benchmarks put $500,000 of 20-year term at about $213 a year for a man and $182 for a woman (NerdWallet, Oct 2026). Price rises with age, tobacco use and health class, which is why quoting across carriers matters.
Can I get term life without a medical exam?
Yes. Accelerated underwriting lets qualifying applicants skip the exam at standard rates — Legal & General America up to $4,000,000, Ethos up to $3,000,000, Foresters up to $2,000,000 (ages 18–60), Fidelity Life InstaBrain up to $1,000,000 — because the carrier checks prescription, driving and medical-information records electronically. An exam can still be required if the data does not line up.
What happens when the term ends?
Coverage ends with no payout. Most policies let you renew year-to-year at much higher premiums or convert to permanent coverage before a deadline set by the carrier (NAIC Buyer's Guide).
Is the death benefit taxed?
Generally no. Proceeds paid because of the insured's death are excluded from the beneficiary's gross income under IRC §101(a); only interest earned on proceeds is taxable (IRS).
Request Your Term Quotes
A licensed agent compares the carriers we represent for your age, state and health, then emails or texts the numbers. No obligation.